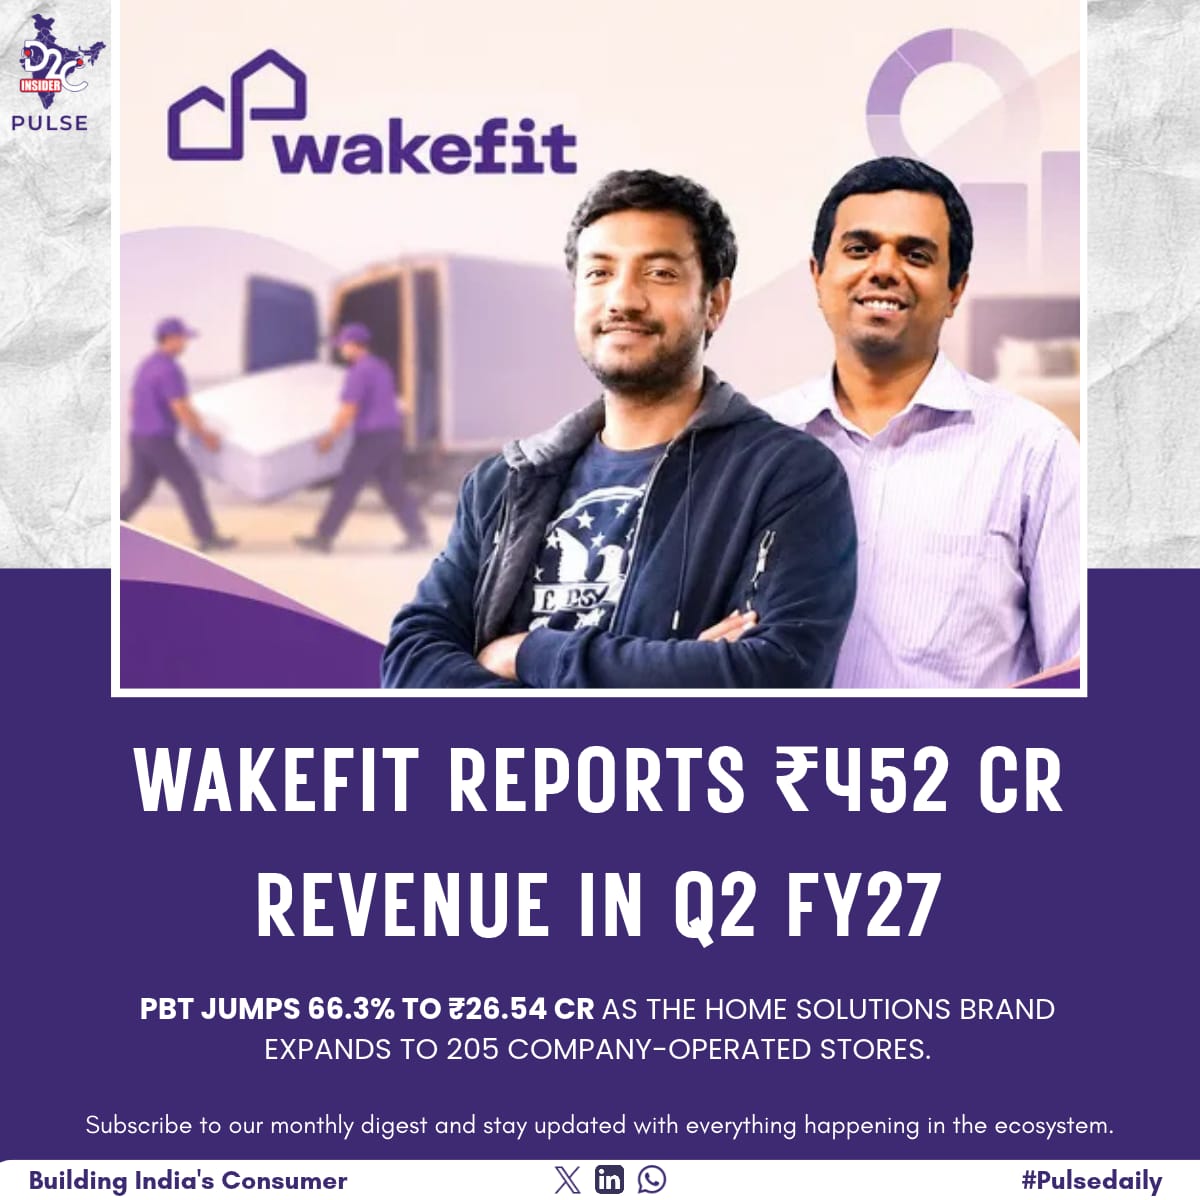
Wakefit Innovations reported a strong second quarter for FY27, with revenue from operations rising 19.9% year-on-year to ₹451.99 crore and profit before tax (PBT) increasing 66.3% to ₹26.54 crore. The Bengaluru-based home and sleep solutions company also recorded its highest-ever quarterly revenue, supported by growth across its mattress and furniture categories and an expanding offline retail network.
The results, for the quarter ended September 30, 2026, reflect continued momentum in Wakefit’s omnichannel business model, which combines its direct-to-consumer website, company-operated stores and external retail channels.
However, the improvement in PBT did not translate into higher reported net profit for the quarter. Profit after tax (PAT) stood at ₹15.89 crore, marginally lower than ₹15.96 crore in Q2 FY26. The difference was partly driven by a deferred tax expense of ₹6.43 crore recorded during the quarter. Excluding this deferred tax charge, the company reported PAT of ₹22.32 crore, up 39.9% year-on-year.
Reported EBITDA, excluding other income, increased 21.5% to ₹50.15 crore, with the margin improving marginally to 11.1% from 11% a year earlier. Operating EBITDA, which excludes lease-related adjustments, ESOP charges and certain other items, rose 25.8% to ₹30.5 crore, with its margin expanding to 6.7% from 6.4%.
Retail expansion and category growth support revenue
Wakefit’s physical retail expansion remained a significant contributor to its growth strategy. The company added 41 company-owned, company-operated (COCO) stores during Q2 FY27, taking its total network to 205 stores across 137 cities and 22 states. Its multi-brand outlet network also expanded to 2,589 stores across 787 cities.
The retail channel recorded approximately 24% year-on-year growth during the quarter. Own channels, comprising the company’s website and COCO stores, accounted for 70% of Q2 revenue, while external channels contributed the remaining 30%.
Mattresses continued to anchor the business, accounting for 61.8% of quarterly sales. Furniture contributed 30.1%, while furnishings made up 8.1%. On a year-on-year basis, mattress revenue grew 21.4% and furniture revenue increased 24.9%. Repeat customers contributed 32.4% of revenue during the quarter, indicating the importance of customer retention alongside new customer acquisition.
Rising input costs remain a key monitorable
Despite the revenue and operating profit growth, Wakefit faced pressure from higher raw material costs. Its gross margin declined to 53.9% in Q2 FY27 from 57.7% in the corresponding quarter last year. The company attributed the compression primarily to a sharp increase in the prices of Polyol and TDI, key inputs used in its mattress manufacturing operations.
Wakefit said it had introduced calibrated price increases to protect absolute profitability while maintaining product affordability. The company also highlighted that festive sales began in the second week of October this year, compared with late September last year, shifting a portion of festive demand from Q2 to Q3.
For the first half of FY27, revenue from operations increased 18.4% to ₹856.90 crore from ₹724 crore in H1 FY26. PBT grew 76.7% to ₹62.85 crore, while PAT rose 10.4% to ₹39.27 crore. Excluding deferred tax, H1 PAT stood at ₹53 crore, up 49% year-on-year.
With 205 company-operated stores, a growing multi-brand outlet network and continued investment in retail expansion, Wakefit is strengthening its position in India’s organised home and furnishings market. The next phase will depend on how effectively it converts this expanding reach into sustained revenue growth while managing raw material inflation, protecting margins and improving profitability.
Sources: Wakefit Innovations’ Q2 and H1 FY27 investor release and investor presentation filed with NSE; FY26 annual disclosures and previous earnings call transcript.